
Foreign grantor trust owner statement
The Instructions for Form 3520-A identify the Foreign Grantor Trust Owner Statement as pages 3 and 4 of the foreign trust's annual information return. The instructions explain who receives it and how it connects to Form 3520.
Where the statement appears
The Instructions for Form 3520-A describe the statement as pages 3 and 4 of that annual return for a foreign trust with at least one U.S. owner. The trust prepares a separate statement for each U.S. owner, and includes each statement with Form 3520-A filed with the IRS.[2]
The statement is furnished to each U.S. person treated as an owner under the grantor trust rules. The instructions distinguish it from the Foreign Grantor Trust Beneficiary Statement, which is for a U.S. beneficiary receiving a distribution. A person treated as owner for a portion of the trust receives the owner statement for that portion instead of the beneficiary statement.[2]
The Form 3520 instructions connect the statement to Part II, U.S. Owner of a Foreign Trust. A U.S. person considered owner of any trust assets under sections 671 through 679 completes that part even if no trust transactions occurred during the tax year.[1]
Delivery and related reporting
The foreign trust generally furnishes the owner statement by the due date of Form 3520-A, and includes it with that return. The instructions allow a later furnishing when an extension applies. If the trust does not file Form 3520-A, the U.S. owner files a substitute Form 3520-A with Form 3520 by the Form 3520 due date, including the owner statement.[2]
On Form 3520, the owner indicates whether the trust filed Form 3520-A and attaches pages 3 and 4 when the answer is yes. If the statement was not received, the instructions direct the owner to report the trust asset value on line 23 to the best of the owner's ability and use Form 8082 to notify the IRS about the missing statement.[1]
The owner statement also differs in purpose from the separate Statement of Foreign Trust Income Attributable to U.S. Owner. The latter's amounts include the trust income reported as attributable to the U.S. owner, and the trust may provide further information for reporting income and expenses on the owner's U.S. income tax return.[2]
Information about the statement
The owner statement is part of the information the foreign trust supplies about its U.S. owners. The trust prepares a separate statement for each U.S. owner.[2]
The related Form 3520 reporting identifies the person considered owner of each portion and the Code section that treats that person as owner for U.S. income tax purposes. It also asks for the fair market value of assets treated as owned, with liabilities disregarded.
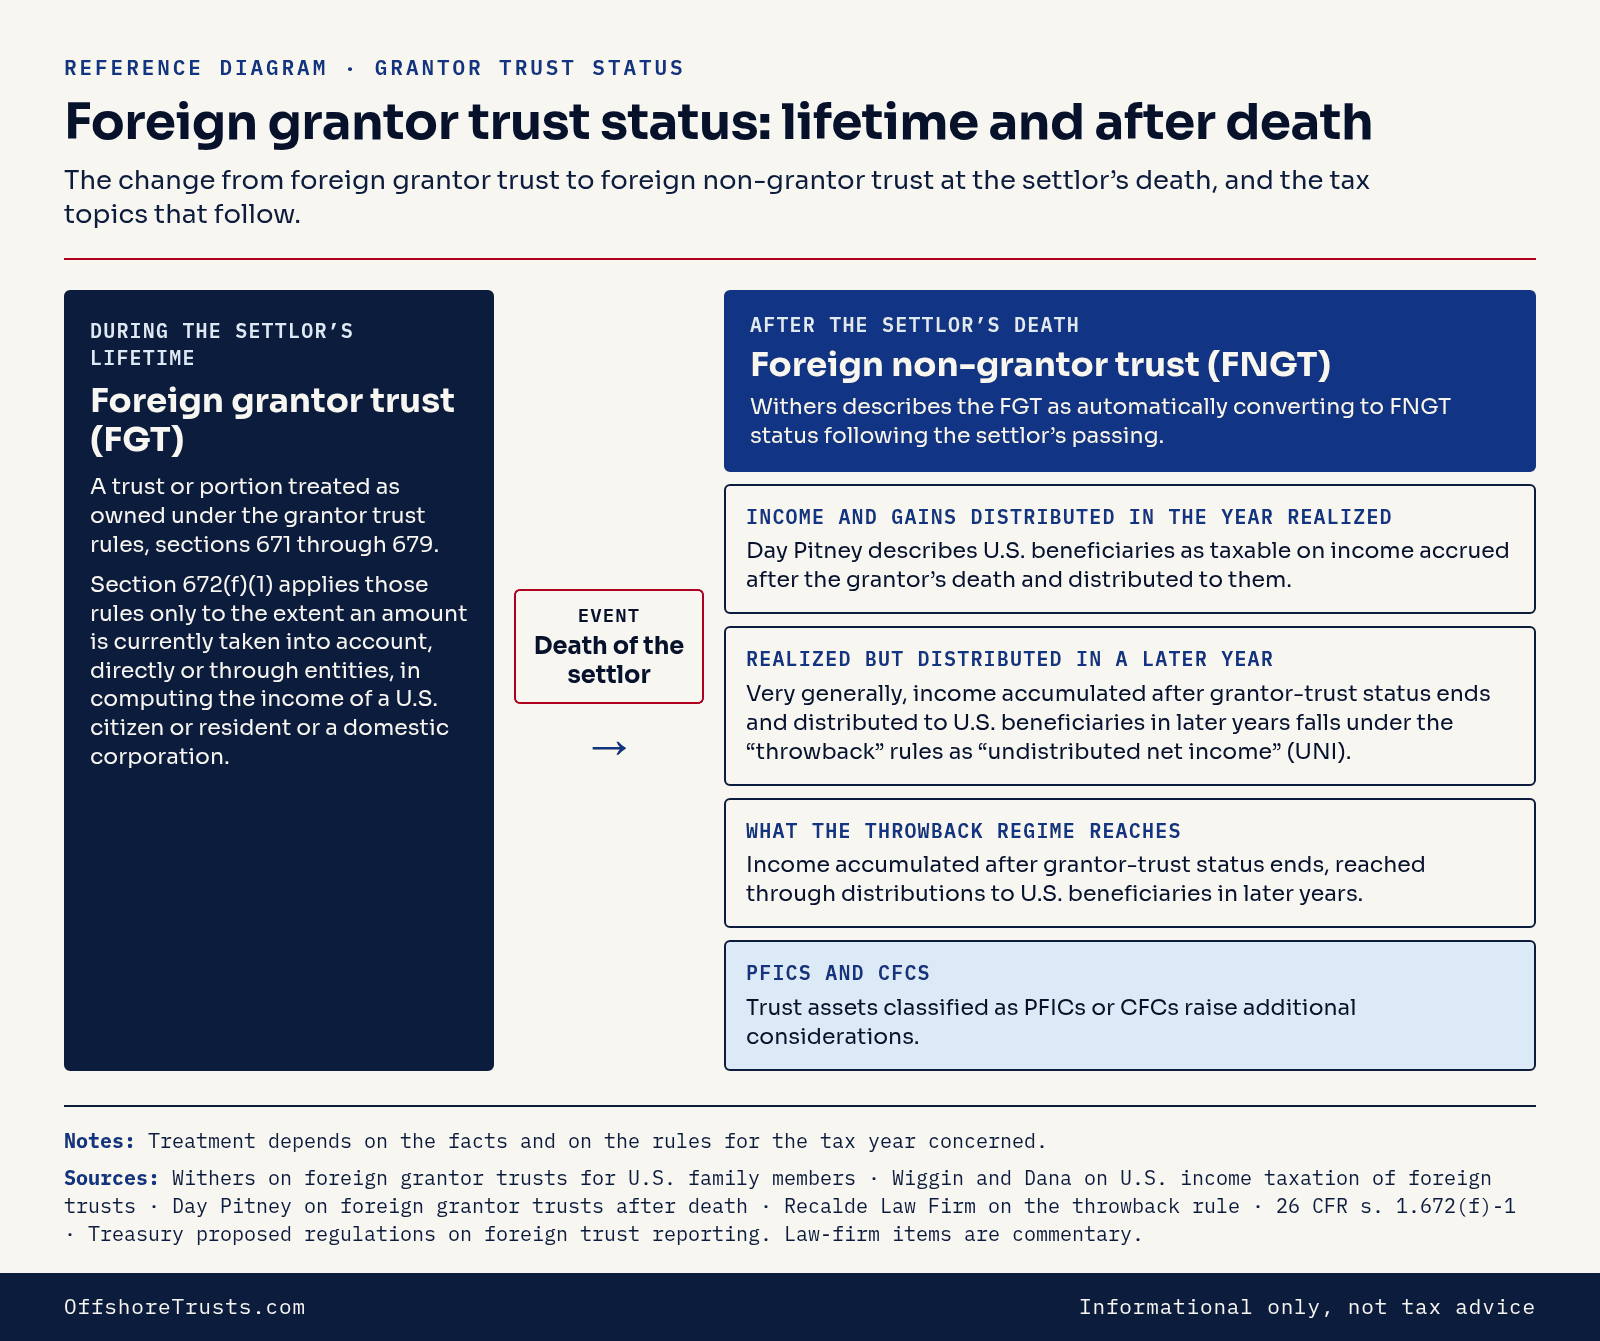
Data table for this infographic
| Stage or topic | Status or event | Description | Tax treatment or reporting |
|---|---|---|---|
| During the settlor's lifetime | Foreign grantor trust (FGT) | A trust or portion treated as owned under the grantor trust rules, sections 671 through 679. | Section 672(f)(1) applies those rules only to the extent an amount is currently taken into account, directly or through entities, in computing the income of a U.S. citizen or resident or a domestic corporation. |
| Event | Death of the settlor | Grantor trust status generally ends at the settlor's death. | |
| After the settlor's death | Foreign non-grantor trust (FNGT) | The trust generally becomes a foreign non-grantor trust after the settlor's death. | |
| What the throwback regime reaches | Income accumulated after grantor-trust status ends, reached through distributions to U.S. beneficiaries in later years. | ||
| Notes | Treatment depends on the facts and on the rules for the tax year concerned. | ||
Income and gains distributed in the year realized: Distributions to U.S. beneficiaries of income accrued after the grantor's death are generally included in their income under the rules for foreign non-grantor trusts.
Realized but distributed in a later year: Very generally, income accumulated after grantor-trust status ends and distributed to U.S. beneficiaries in later years falls under the "throwback" rules as "undistributed net income" (UNI).
PFICs and CFCs: Trust assets classified as PFICs or CFCs raise additional considerations.
Questions and answers
Which form contains the Foreign Grantor Trust Owner Statement?
It is pages 3 and 4 of Form 3520-A. The foreign trust includes it with its annual information return and furnishes it to each U.S. owner.[2]
Who receives an owner statement?
The statement goes to each U.S. person treated as an owner of a portion of the foreign trust under the grantor trust rules. The instructions call for a separate statement for each such owner.[2]
How does the statement relate to Form 3520?
The U.S. owner attaches pages 3 and 4 to Form 3520 when the foreign trust filed Form 3520-A. If the trust did not file, the owner files a substitute Form 3520-A with Form 3520.[1]
What if the U.S. owner does not receive the statement?
The Form 3520 instructions say to enter the fair market value of trust assets treated as owned to the best of the owner's ability. Form 8082 notifies the IRS that the statement was not received.[1]
How is the owner statement different from the beneficiary statement?
The owner statement is furnished to a U.S. person treated as owner of a trust portion. The beneficiary statement applies to a U.S. beneficiary receiving a distribution, except for any portion of which that person is treated as owner.[2]
Related terms
- Foreign grantor trust beneficiary statement: A foreign grantor trust beneficiary statement appears on page 5 of Form 3520-A. It reports distributions to U.S. beneficiaries and identifies the trust's owner.
- Substitute Form 3520-A: A substitute Form 3520-A is filed by a U.S. owner when a foreign trust fails to file its annual return, and it carries its own timing and statement rules.
- U.S. owner of a foreign trust: The Form 3520 instructions define a U.S. owner as a person treated as owning trust assets under grantor trust rules. Ownership can apply to part of a trust.
- Foreign grantor trust: A foreign grantor trust is a foreign trust treated as owned by a grantor, often a U.S. person. Ownership brings Form 3520 and Form 3520-A reporting duties.
Related guides and articles
- Foreign trust forms and the accounts behind them: Forms 3520 and 3520-A cover transfers to a foreign trust, its ownership and its distributions. Bank accounts behind a trust add separate FBAR and 8938 rules.
- Section 6048 reporting for certain foreign trusts: Section 6048 foreign trust reporting for U.S. citizens, including definitions and reportable events, as well as ownership and distributions and the IRS forms.
- Section 679 and foreign trusts with U.S. beneficiaries: Section 679 covers ownership treatment, U.S. beneficiaries, transfer exceptions and related reporting rules for foreign trusts connected to U.S. citizens.
Related pages
Sources and data notes
- Internal Revenue Service, Instructions for Form 3520. https://www.irs.gov/instructions/i3520. Retrieved .
- Internal Revenue Service, Instructions for Form 3520-A. https://www.irs.gov/instructions/i3520a. Retrieved .
- Internal Revenue Service, 26 CFR 301.7701-7 Trusts, domestic and foreign. https://ecfr.io/Title-26/Section-301.7701-7. Retrieved .
- Internal Revenue Service, 26 CFR 301.7701-4 Trusts. https://www.ecfr.gov/current/title-26/section-301.7701-4. Retrieved .
- Internal Revenue Service, 26 U.S.C. 679. https://uscode.house.gov/us/usc/119-118/t26/s679/. Retrieved .
- Internal Revenue Service, 26 U.S.C. 6048. https://uscode.house.gov/us/usc/119-118/t26/s6048/. Retrieved .
- Internal Revenue Service, Foreign trust reporting requirements and tax consequences. https://www.irs.gov/businesses/international-businesses/foreign-trust-reporting-requirements-and-tax-consequences. Retrieved .
Dates in this block record when each source was read for this page.