
Foreign trust loan
The Form 3520 instructions describe how certain loans involving a foreign trust are treated for reporting.
Meaning in the Form 3520 instructions
The IRS instructions for Form 3520 describe a foreign trust loan as a direct or indirect loan of cash or marketable securities to a grantor or beneficiary, including a loan to a related U.S. person.[1]
A U.S. person who is an owner or beneficiary is within the stated filing description when that person or a related U.S. person receives such a loan during the tax year.
Reporting treatment
The distinction between reporting and tax treatment matters here. Where the trust has a U.S. transferor and the loan is not repaid at a market rate of interest within a reasonable period, the instructions say it remains reportable on Part III even though it is not treated as a taxable distribution under section 643(i).[1]
Uncompensated use of foreign trust property is a neighboring rule, not a loan. The instructions treat the fair market value of that use as a reportable distribution, with the amount paid taken into account in the line 25 calculation.[1]
Qualified obligations and related terms
A qualified obligation is a separate category that can affect how an obligation exchanged for a transfer or loan is reported. Among other requirements, the proposed regulations require a qualified obligation to be in writing with a term of five years or less. All payments must be made in cash in U.S. dollars. The U.S. person also reports the obligation's status, including principal and interest payments, while it remains outstanding.[1]
The instructions also require an agreement to extend the assessment period for relevant tax attributable to the transfer and consequential changes, subject to an exception when the obligation matures by the end of the tax year and is paid within that period. Under the proposed regulations, an obligation that ceases to qualify is treated as a section 643(i) distribution to the U.S. grantor or beneficiary. The proposed regulations generally require a U.S. person receiving a foreign trust distribution to report it on Part III of Form 3520, subject to exceptions.[1]
For a loan received from a related foreign trust, the filer answers line 25's question about whether the exchanged obligation is qualified. The instructions assign an obligation a fair market value of zero if it is not qualified. A qualified obligation therefore relates to the loan's reporting fields, while the loan itself remains part of the distribution reporting rules.[1]
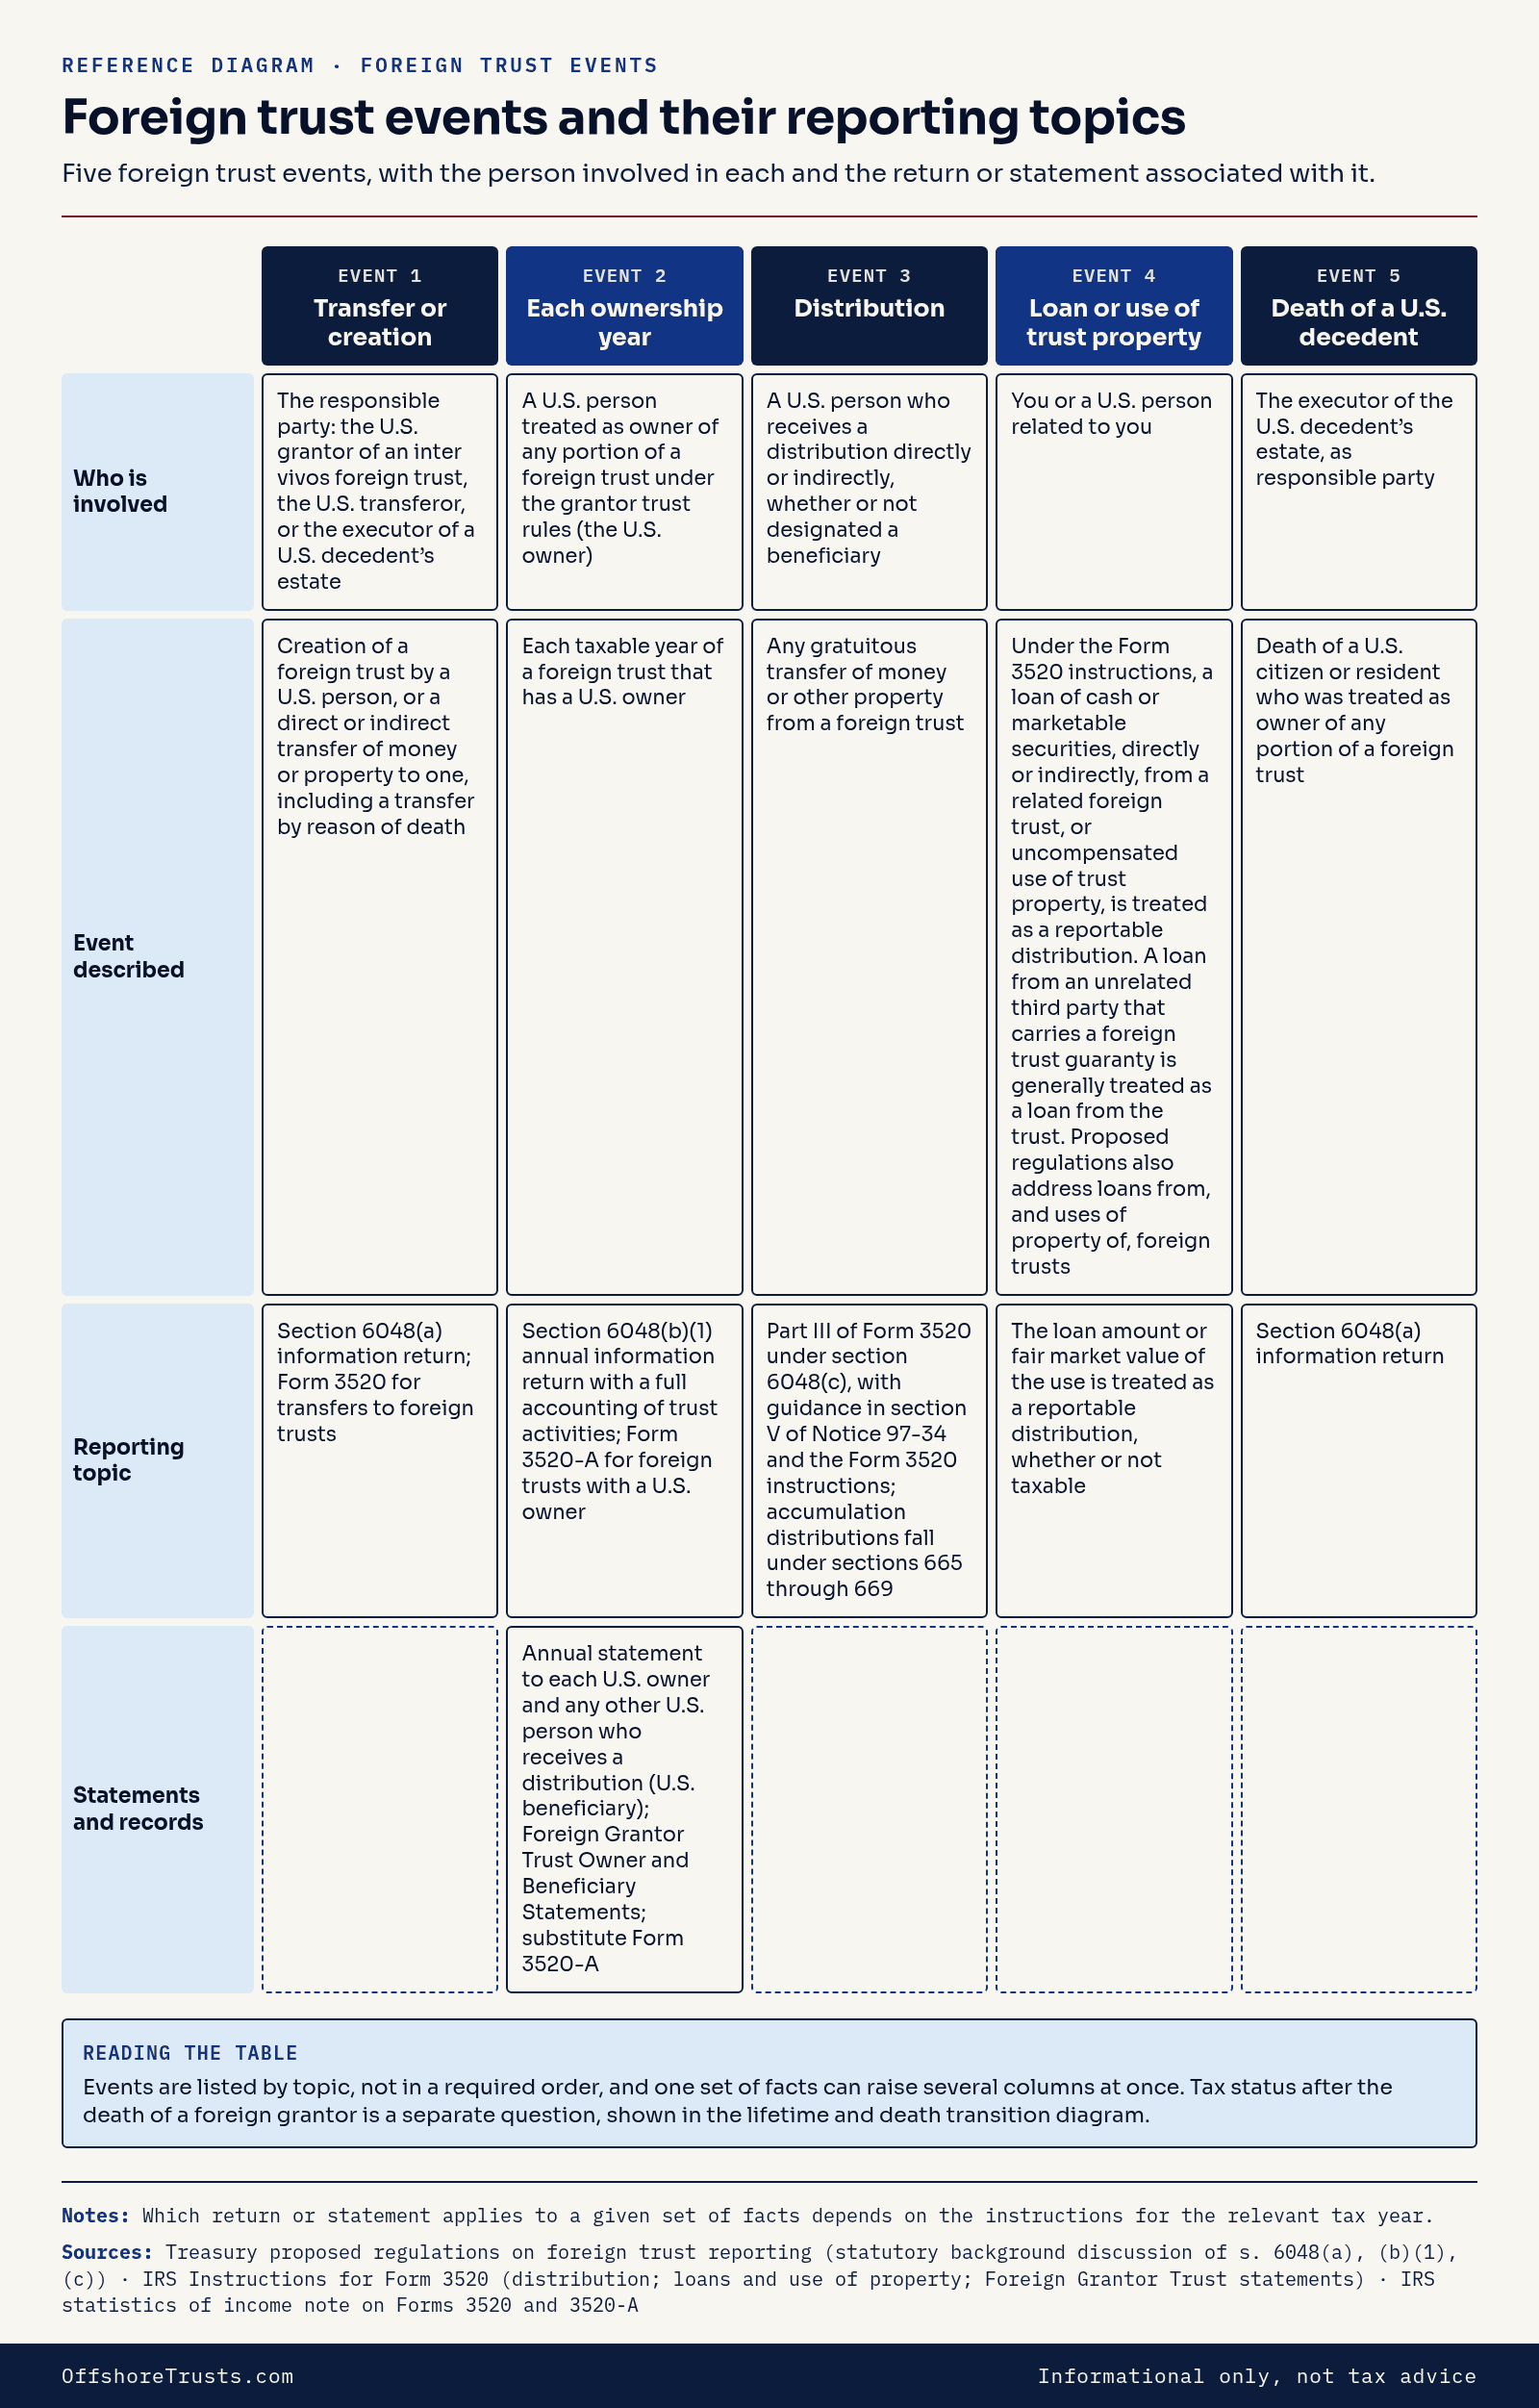
Data table for this infographic
| Event group | Event described | Who is involved | Reporting topic | Statements and records |
|---|---|---|---|---|
| Transfer or creation | Creation of a foreign trust by a U.S. person, or a direct or indirect transfer of money or property to one, including a transfer by reason of death | The responsible party: the U.S. grantor of an inter vivos foreign trust, the U.S. transferor, or the executor of a U.S. decedent's estate | Section 6048(a) information return; Form 3520 for transfers to foreign trusts | Not covered |
| Each ownership year | Each taxable year of a foreign trust that has a U.S. owner | A U.S. person treated as owner of any portion of a foreign trust under the grantor trust rules (the U.S. owner) | Section 6048(b)(1) annual information return with a full accounting of trust activities; Form 3520-A for foreign trusts with a U.S. owner | Annual statement to each U.S. owner and any other U.S. person who receives a distribution (U.S. beneficiary); Foreign Grantor Trust Owner and Beneficiary Statements; substitute Form 3520-A |
| Distribution | Any gratuitous transfer of money or other property from a foreign trust | A U.S. person who receives a distribution directly or indirectly, whether or not designated a beneficiary | Part III of Form 3520 under section 6048(c), with guidance in section V of Notice 97-34 and the Form 3520 instructions; accumulation distributions fall under sections 665 through 669 | Not covered |
| Loan or use of trust property | Under the Form 3520 instructions, a loan of cash or marketable securities, directly or indirectly, from a related foreign trust, or uncompensated use of trust property, is treated as a reportable distribution. A loan from an unrelated third party that carries a foreign trust guaranty is generally treated as a loan from the trust. Proposed regulations also address loans from, and uses of property of, foreign trusts. | You or a U.S. person related to you | The loan amount or fair market value of the use is treated as a reportable distribution, whether or not taxable | Not covered |
| Death of a U.S. decedent | Death of a U.S. citizen or resident who was treated as owner of any portion of a foreign trust | The executor of the U.S. decedent's estate, as responsible party | Section 6048(a) information return | Not covered |
| Reading the table | Events are listed by topic, not in a required order, and one set of facts can raise several columns at once. | Tax status after the death of a foreign grantor is a separate question, shown in the lifetime and death transition diagram. | ||
Questions and answers
When does the Form 3520 guidance treat a trust loan as a distribution?
Under the proposed rule, a foreign trust loan of cash or marketable securities made directly or indirectly to a U.S. grantor or beneficiary, or a related U.S. person, is generally treated as a distribution to the U.S. grantor or beneficiary unless an exception applies. The Form 3520 instructions treat such loans from a related foreign trust as reportable distributions whether or not taxable.[1]
What requirements do the 2024 proposed regulations describe for a qualified obligation?
Among other requirements, the obligation must be in writing, have a term of five years or less, and require all payments in cash in U.S. dollars. The proposal also requires annual reporting of the obligation's status, including principal and interest payments, on Part III of Form 3520 while it remains outstanding.[8]
Does reporting a loan mean it is a taxable distribution?
No. The instructions state that a loan may remain reportable on Form 3520 Part III while not being treated as a taxable distribution under section 643(i), when the described U.S.-transferor and repayment conditions apply.[1]
Related terms
- Qualified obligation: The Form 3520 instructions define a qualified obligation through written terms, a maximum term, U.S. dollar payments, an interest yield, and ongoing reporting.
- Uncompensated use of trust property: Uncompensated use of foreign trust property by a U.S. person or a related U.S. person is treated as a distribution at fair market value and is reportable.
- Related person: Related persons are defined through sections 267 and 707(b) in the Form 3520 instructions. Examples include family members and majority-owned corporations.
- Distribution from a foreign trust: A foreign trust distribution triggers section 6048(c) reporting for the U.S. person who receives it. Related reporting and tax terms explain how it is treated.
Related guides and articles
- Foreign trust loans and use of property: For a U.S. citizen, IRS instructions treat certain loans from a related foreign trust and uncompensated use of trust property as reportable distributions.
- Section 679 and foreign trusts with U.S. beneficiaries: Section 679 covers ownership treatment, U.S. beneficiaries, transfer exceptions and related reporting rules for foreign trusts connected to U.S. citizens.
- When a Foreign Trust Has a U.S. Beneficiary: A property transfer to a foreign trust generally means it has a U.S. beneficiary. Rules also address trust terms, loans, property use, and transfer reporting.
Related pages
Sources and data notes
- Internal Revenue Service, Instructions for Form 3520. https://www.irs.gov/instructions/i3520. Retrieved .
- Internal Revenue Service, Instructions for Form 3520-A. https://www.irs.gov/instructions/i3520a. Retrieved .
- Internal Revenue Service, 26 CFR 301.7701-7 Trusts, domestic and foreign. https://ecfr.io/Title-26/Section-301.7701-7. Retrieved .
- Internal Revenue Service, 26 CFR 301.7701-4 Trusts. https://www.ecfr.gov/current/title-26/section-301.7701-4. Retrieved .
- Internal Revenue Service, 26 U.S.C. 679. https://uscode.house.gov/us/usc/119-118/t26/s679/. Retrieved .
- Internal Revenue Service, 26 U.S.C. 6048. https://uscode.house.gov/us/usc/119-118/t26/s6048/. Retrieved .
- Internal Revenue Service, Foreign trust reporting requirements and tax consequences. https://www.irs.gov/businesses/international-businesses/foreign-trust-reporting-requirements-and-tax-consequences. Retrieved .
- U.S. Department of the Treasury and Internal Revenue Service, Federal Register, Volume 89 Issue 90, proposed regulations on foreign trust reporting (2024-09434). https://www.govinfo.gov/content/pkg/FR-2024-05-08/html/2024-09434.htm. Retrieved .
Dates in this block record when each source was read for this page.