
FBAR
FinCEN describes the FBAR filing rule for U.S. persons with foreign financial accounts.
Meaning and filing threshold
The FBAR is a report required when a U.S. person has a financial interest in or signature authority over foreign financial accounts whose aggregate value exceeds $10,000 at any time during the calendar year.[2]
The regulation defines a U.S. person to include a U.S. citizen, a U.S. resident, and certain entities formed under U.S. law. It defines foreign country by reference to geographic areas outside the United States.[3]
Accounts and interests covered
The regulation identifies bank accounts, securities accounts, and certain other financial accounts as reportable account types. Other accounts include cash value insurance or annuity policies, certain futures or options accounts, and mutual funds or similar pooled funds with public shares, regular net asset values, and regular redemptions.[3]
A U.S. person has a financial interest in an account held in their name, including an account held jointly. The definition also reaches accounts legally held by agents acting on the person's behalf, certain entities in which the person owns more than 50 percent, and trusts under specified grantor or beneficiary conditions.[3]
Signature or other authority means the ability, alone or with another person, to direct the disposition of money or other assets in an account through direct communication with the institution.[3]
Exceptions and special rules
The regulation excludes certain government accounts, international financial institution accounts, U.S. military banking facilities abroad, and bank correspondent or nostro accounts used solely for bank-to-bank settlements.[3]
Some officers or employees do not report signature authority over an employer's account when they have no financial interest and the employer meets the specified regulatory conditions. Participants and beneficiaries in listed retirement plans and IRAs are also exempt for accounts held by or on behalf of those plans or accounts.[3]
The FBAR instructions state that a trust beneficiary with a financial interest based on a greater than 50 percent present beneficial interest in the trust's assets or income need not report the trust's foreign accounts if the trust, trustee, or agent is a U.S. person and files an FBAR disclosing those accounts. A person with a financial interest in 25 or more accounts reports only the number of accounts and basic information on the FBAR, and must provide detailed account information if FinCEN or its delegate asks.[3]
Relationship to Form 8938
The IRS instructions state that filing Form 8938 does not remove an FBAR filing requirement that otherwise applies. Form 8938 reports specified foreign financial assets above its applicable threshold, while the FBAR has its own aggregate account value threshold and coverage test.[1]
The two reports are separate reporting regimes. The IRS directs readers to FinCEN Form 114 and its instructions for FBAR filing requirements.[1]
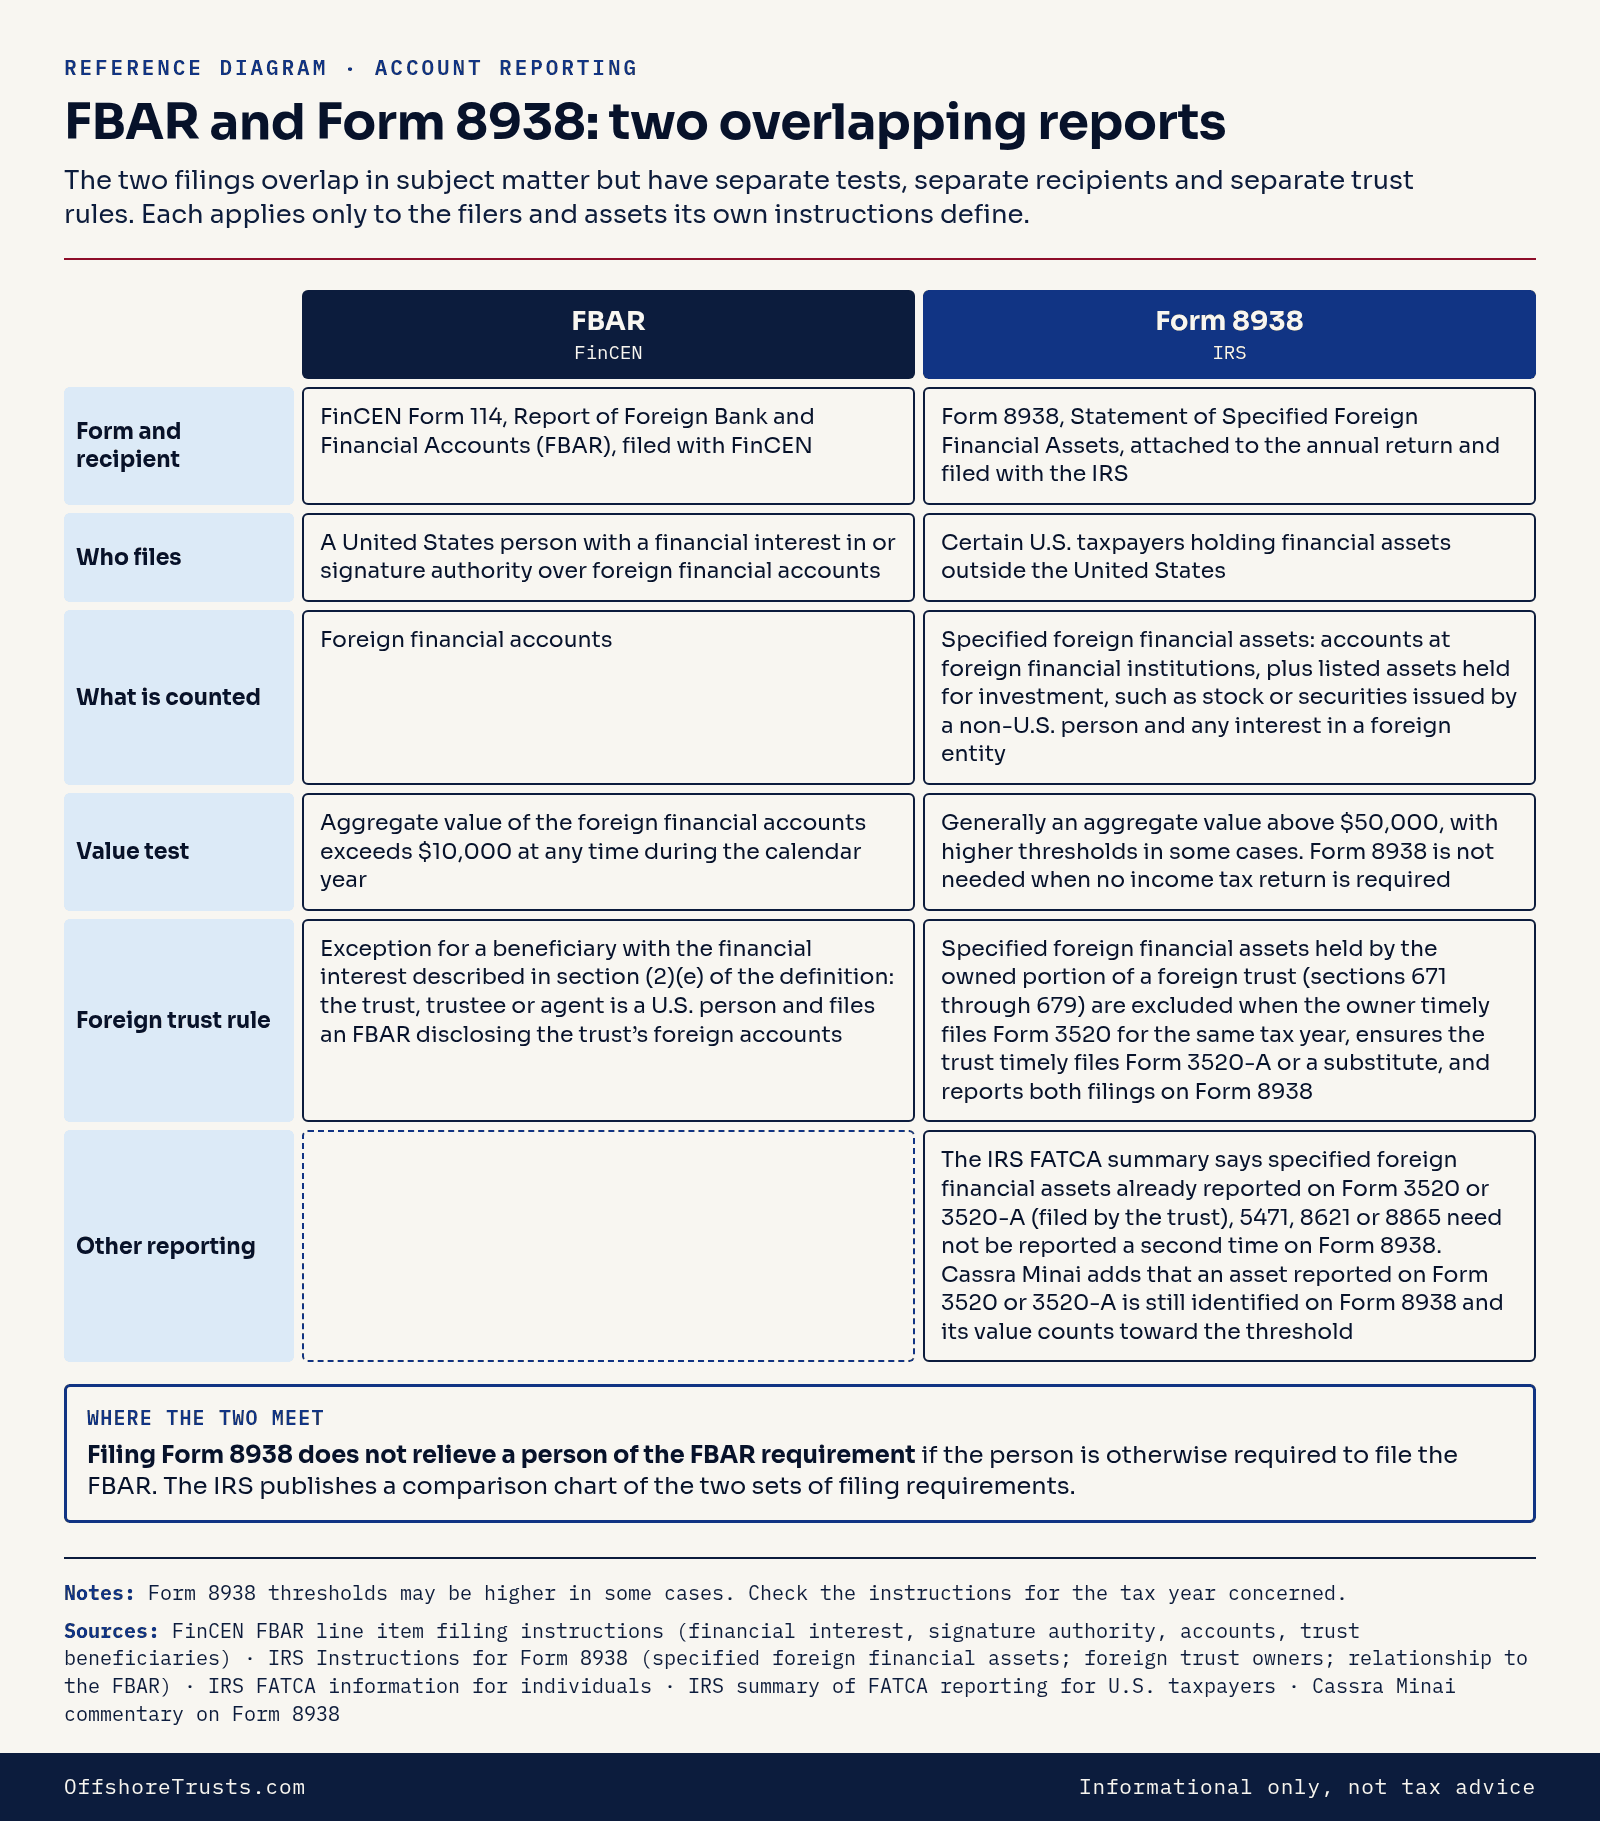
Data table for this infographic
| Topic | FBAR | Form 8938 |
|---|---|---|
| Summary | The two filings overlap in subject matter but have separate tests, separate recipients and separate trust rules. | |
| Form and recipient | FinCEN Form 114, Report of Foreign Bank and Financial Accounts (FBAR), filed with FinCEN | Form 8938, Statement of Specified Foreign Financial Assets, attached to the annual return and filed with the IRS |
| Who files | A United States person with a financial interest in or signature authority over foreign financial accounts | Certain U.S. taxpayers holding financial assets outside the United States |
| What is counted | Foreign financial accounts | Specified foreign financial assets: accounts at foreign financial institutions, plus listed assets held for investment, such as stock or securities issued by a non-U.S. person and any interest in a foreign entity |
| Value test | Aggregate value of the foreign financial accounts exceeds $10,000 at any time during the calendar year | Generally an aggregate value above $50,000, with higher thresholds in some cases. Form 8938 is not needed when no income tax return is required |
| Foreign trust rule | Exception for a beneficiary whose financial interest in a trust account rests on a present beneficial interest in more than 50 percent of the trust assets or current income: no filing is needed when the trust, trustee or agent is a U.S. person and files an FBAR disclosing the trust's foreign accounts | Specified foreign financial assets held by the owned portion of a foreign trust (sections 671 through 679) are excluded when the owner timely files Form 3520 for the same tax year, ensures the trust timely files Form 3520-A or a substitute, and reports both filings on Form 8938 |
| Other reporting | Specified foreign financial assets already reported on Form 3520 or 3520-A (filed by the trust), 5471, 8621 or 8865 need not be reported a second time on Form 8938. The asset is still identified on Form 8938, and its value counts toward the threshold. | |
| Where the two meet | Filing Form 8938 does not relieve a person of the FBAR requirement if the person is otherwise required to file the FBAR. The IRS publishes a comparison chart of the two sets of filing requirements. | |
| Notes | Form 8938 thresholds may be higher in some cases. The instructions for the tax year concerned govern. | |
| Sources | FinCEN FBAR line item filing instructions (financial interest, signature authority, accounts, trust beneficiaries) · IRS Instructions for Form 8938 (specified foreign financial assets; foreign trust owners; relationship to the FBAR) · IRS FATCA information for individuals · IRS summary of FATCA reporting for U.S. taxpayers · Cassra Minai commentary on Form 8938 | |
FinCEN Form 114
FinCEN Form 114 is the Report of Foreign Bank and Financial Accounts, known as the FBAR. The federal regulation describes the filing obligation for a United States person with a financial interest in, or signature or other authority over, certain foreign accounts. Signature or other authority means an individual's authority, alone or with another person, to control the disposition of money, funds or other assets held in a financial account through direct communication with the person maintaining the account.[1][3]
The regulation also specifies circumstances involving accounts legally held by agents or trusts. For a trust, a U.S. person has a financial interest if that person is the grantor with a federal tax ownership interest, has a present beneficial interest in more than half its assets, or receives more than half its current income.[3]
Exceptions include accounts of specified U.S. government entities and international financial institutions of which the U.S. government is a member. Certain retirement plan participants and beneficiaries, and IRA owners and beneficiaries, need not report accounts held by or for the plan or IRA. A beneficiary of a specified trust need not report its foreign accounts when a U.S. trust, trustee, or agent files a report disclosing them.[3]
FinCEN Form 114 and IRS Form 8938 are separate reporting requirements. Filing Form 8938 does not remove an FBAR requirement that otherwise applies. Form 8938 is attached to an annual return under its own instructions. FinCEN describes individual filers as people who personally own, or jointly own with a spouse, a reportable foreign account. Individuals may submit the FBAR electronically through the BSA E-Filing System without registering for a BSA E-Filing account.[1][2]
Questions and answers
Does Form 8938 replace an FBAR?
No. The IRS instructions say Form 8938 filing does not remove an FBAR obligation that otherwise applies. The FBAR has its own filing test under FinCEN's rules.[1]
What value threshold does FinCEN give for an FBAR?
FinCEN states that filing applies when aggregate foreign account value exceeds $10,000 at any time during the calendar year. The rule concerns accounts in which the U.S. person has a financial interest or over which the person has signature authority.[2]
Does signature authority count even without account ownership?
Yes. Signature authority over a foreign financial account can trigger an FBAR filing requirement even without a financial interest in the account. The regulation defines that authority as control over disposition of account funds or assets through direct communication with the institution maintaining the account.[2]
Can a trust beneficiary have an FBAR exception?
A beneficiary of a qualifying trust need not report the trust's foreign accounts if a U.S. trust, trustee, or agent files a report disclosing them. The regulation limits this exception to the trust described in its specified beneficiary rule.[3]
Related terms
- Signature authority over an account: The FBAR rules define signature authority by the power to direct disposition of account funds through direct communication with the financial institution.
- Foreign financial account: Form 8938 treats an account outside the United States as a specified foreign financial asset. FBAR rules identify reportable accounts by type and location.
- Financial interest in an account: FBAR rules define financial interest through account ownership or relationships to the legal title holder. A U.S. person named on an account has an interest.
Related guides and articles
- FBAR Rules for Trust Beneficiaries: A reference for U.S. citizens on the FBAR value threshold, financial interests, signature authority, and the reporting rule for certain trust beneficiaries.
- FBAR and Form 8938 for accounts linked to trusts: FBAR and Form 8938 are separate reports with different filing tests for a U.S. citizen.
- The FBAR: reporting foreign financial accounts: FBAR reporting for U.S. citizens covers foreign financial accounts, the reporting threshold and filing exceptions, as well as submission and recordkeeping.
Related pages
Sources and data notes
- Internal Revenue Service, Instructions for Form 8938. https://www.irs.gov/instructions/i8938. Retrieved .
- FinCEN, Report foreign bank and financial accounts. https://www.fincen.gov/report-foreign-bank-and-financial-accounts. Retrieved .
- U.S. Government, 31 CFR 1010.350. https://ecfr.io/Title-31/Section-1010.350. Retrieved .
- Internal Revenue Service, FATCA summary. https://www.irs.gov/businesses/corporations/summary-of-key-fatca-provisions. Retrieved .
- U.S. Department of the Treasury, FATCA: agreements by jurisdiction. https://home.treasury.gov/policy-issues/tax-policy/foreign-account-tax-compliance-act. Retrieved .
- Internal Revenue Service, 26 CFR 1.1471-4. https://www.irs.gov/instructions/iw9. Retrieved .
Dates in this block record when each source was read for this page.